
Donors
If you owe federal income tax, you may be able to redirect up to $1,700 a year to scholarships, or $3,400 if you file jointly and each spouse gives, dollar for dollar.
Give through Multiply GoodNew federal scholarship tax credit · Begins January 1, 2027
A new federal law lets you direct up to $1,700 of your taxes to scholarships that help children attend the school that's right for them, including faith-based and Catholic schools, or $3,400 if you file jointly and each spouse gives. Aspergillium proudly helps families and donors get started with Multiply Good.
Subject to IRS guidance and state participation. Not tax advice.
The bigger picture: by 2030, Treasury and the IRS estimate the program could see more than 11 million taxpayers giving nearly $26 billion a year, funding as many as 2.2 million scholarships each year.
Sources: IRC §25F; proposed IRS rules (Oct 2, 2026); Treasury/IRS news release IR-2026-117 (Oct 1, 2026). Estimates are projections, not guarantees.
For donors
The Educational Choice for Children Act, enacted in 2025, created a new federal tax credit (Section 25F of the Internal Revenue Code). Here's the simple version.
Get started at Multiply Good and make a cash gift of up to $1,700, or $3,400 on a joint return when each spouse gives. To qualify for the credit, a gift must go to a Scholarship Granting Organization (SGO) approved in a participating state.
When you file your federal return, claim a dollar-for-dollar credit for your qualifying gift, up to $1,700 per person, or $3,400 on a joint return, against the federal income tax you owe.
Your gift becomes scholarships that help children from working and middle-class families attend the school that fits them best.
For 2027
A gift qualifies for the federal credit only when the scholarship organization is on a list kept by a state that has opted in. Thirty states have made that advance election for 2027. Fourteen states and the District of Columbia are still deciding (New York announced on October 9, 2026 that it will opt in but is not yet on the IRS list), and six have declined so far.
Last checked October 8, 2026 against the IRS list of advance elections (as of September 14, 2026).
Gold states have opted in for 2027. A gift qualifies only when it goes to a scholarship organization on that state's list.
Not final yet: under the proposed IRS rules, each of the 30 states must confirm its election by submitting its list of scholarship organizations by February 15, 2027. A state that doesn't is out for 2027. States that haven't opted in can still do so for 2027 until January 1, 2027.
Where the donor lives does not matter. You can live in a state that is still deciding or has declined, including New Jersey, and still claim the credit by giving to an organization listed in a gold state.
The scholarship itself stays with students who live in the state that listed the organization. It cannot pay for a school change for a student who lives in a state that isn't participating.
Aspergillium is not tied to one organization or one school. The credit can cover qualified K–12 expenses at private schools, charter schools, and public schools, such as tuition, tutoring, and supplies. Homeschool expenses can qualify where that state's law treats the home as a school.
Opted-in states: IRS advance-election list as of September 14, 2026 (page updated September 16; rechecked October 8, 2026). "Still deciding" and "declined" reflect governors' public statements, vetoes, and news reports, and can change. This is not tax advice.
The math
Most charitable gifts reduce your taxable income. This credit is different: it reduces your tax bill itself, dollar for dollar, up to $1,700. A married couple filing jointly can claim up to $3,400 when each spouse gives $1,700.
In other words, money you would have sent to the IRS can instead go to a child's education.
Hypothetical illustration only, for one person. Assumes you owe at least $1,700 in federal income tax, claim no state tax credit or charitable deduction for the same gift, and give to a qualifying SGO. Your total outlay is still $5,000, but $1,700 of it goes to scholarships instead of the Treasury. On a joint return, each spouse can do the same, for a combined credit of up to $3,400.
Protect your credit
A few simple rules decide whether a gift earns the credit. Each card notes whether it comes from the law itself or from the proposed IRS rules.
Under the proposed IRS rules, you designate the gift for the federal credit at the moment you give. That choice can't be changed later.
The law counts only cash gifts. Under the proposed IRS rules, that means a check, an electronic transfer, or an after-tax payroll gift, not stock or digital assets.
Under the proposed IRS rules, the scholarship organization sends a written acknowledgment by January 31 of the next year, with a unique donor number. Keep it for tax time.
Only gifts made on or after January 1, 2027 count toward the credit. A gift made in 2026 doesn't qualify.
The credited amount can't also be deducted as a charitable gift, and any state tax credit for the same gift reduces the federal credit.
Scholarship organizations can't earmark gifts for any particular student, so a gift can't be steered to a specific child, including your own.
General information, not tax advice. Talk with your tax professional about your own situation.
Donors, families, schools & parishes
Wherever you fit, the next step starts at Multiply Good.
If you owe federal income tax, you may be able to redirect up to $1,700 a year to scholarships, or $3,400 if you file jointly and each spouse gives, dollar for dollar.
Give through Multiply GoodScholarships can help with tuition and other qualifying K–12 education expenses, including at Catholic and other faith-based schools. Eligibility is based on household income compared with your area, up to 300% of the area median, so most families in participating states may qualify.
Get started at Multiply GoodA new source of tuition support for the families you serve, and a simple way for alumni and supporters to help at little or no extra cost to themselves.
Get started at Multiply GoodHelp your community see the opportunity: ordinary tax dollars, redirected to lasting good for children and families.
Get started at Multiply GoodStates must opt in each year, and each participating state lists its approved SGOs. Scholarship eligibility rules are set by federal law and the SGO.
Marketing for Multiply Good
Aspergillium is the dedicated marketing partner for Multiply Good. We don't collect gifts or run scholarships; we carry Multiply Good's message to the people and partners who can put it to work.
An aspergillum carries blessing outward from a single source. That's the idea behind our name, and it's how we work: one clear, honest message, carried through four doors, and every door leads to Multiply Good.
Warm, plain-spoken messages on social media first, then in print and broadcast, so families and taxpayers hear about the credit where they already are.
Grants to community organizations, such as parishes, schools, and nonprofits, that rally their communities and help their members take part.
Estate attorneys, insurance professionals, CPAs, and financial advisors learn how the credit works so they can help their clients give with confidence.
An optional payroll gift through platforms like ADP, Paychex, and Workday, so giving happens before the paycheck is spent, with a year-end acknowledgment from the scholarship organization.
Fall 2026
Building partnerships with parishes, schools, and employers.
November 2026
Priority Access opens.
January 1, 2027
The first gifts that count toward the credit.
2027
National rollout, as final IRS rules arrive.
Timing depends on Multiply Good, participating states, and IRS guidance.
What a payroll gift option looks like:
On a joint return, the credit can reach $3,400 only when each spouse makes their own gift, under the proposed IRS rules.
Get started at Multiply GoodFor estate attorneys, insurance professionals, CPAs, and financial advisors:
Each professional follows the standards of their own field. Aspergillium is not a tax advisor.
Get started at Multiply GoodAspergillium does not collect or hold gifts. Gifts go through Multiply Good to qualified scholarship organizations.
Questions
Short answers based on the law and the proposed IRS rules from October 2026.
Individuals who are U.S. citizens or residents and owe federal income tax. Businesses can't claim it, and under the proposed IRS rules, gifts made through partnerships or S corporations don't qualify.
Up to $1,700 per person each year, dollar for dollar against federal income tax. Under the proposed IRS rules, a married couple filing jointly can claim up to $3,400, but only when each spouse makes their own qualifying gift. One spouse can't claim both.
The credit is nonrefundable, so it can't create a refund. Any unused amount carries forward for up to five years.
Yes, if you owe federal income tax for the year. A refund just means more was withheld than you owed. The credit lowers the tax you owe, so the same withholding produces a bigger refund. The credit is nonrefundable, so it can't go below zero tax, but any unused amount carries forward for up to five years.
Possibly. If you plan to give, you may be able to adjust your Form W-4 so less tax is withheld during the year. Talk with a tax professional before changing your withholding.
Under Treasury's proposed rules, any state tax credit you receive for the same gift is subtracted first, and then the $1,700 federal limit applies to what's left. Together, the state and federal benefits can't exceed the amount you gave.
Yes. If you give one scholarship organization more than $5,000 and more than 2% of all the gifts it receives in a year, your family can't receive scholarships from that organization for that year and the following year.
Gifts count starting January 1, 2027. Nothing given in 2026 qualifies.
No. Where you live doesn't matter. What matters is that the scholarship organization is on a participating state's list for the year. The scholarships then go to students who live in that state.
Not for the same dollars. The amount that earns the credit can't also be deducted, and any state tax credit for the same gift reduces the federal credit.
The law counts only cash, so stock doesn't qualify. Under the proposed IRS rules, cash includes checks, electronic transfers, and after-tax payroll gifts, but not digital assets.
No. Scholarship organizations can't earmark gifts for any particular student, including your own child.
Qualified K–12 expenses under federal law, such as tuition, fees, tutoring, special-needs services, books, supplies, computer equipment, and uniforms or transportation a school requires or provides. Treasury plans more detailed guidance on expenses.
Generally no. Federal law excludes these scholarships from income when they're used for qualified K–12 expenses.
The law sets no end date and no national cap on total credits. Congress could still change the law, and the IRS rules are not yet final.
No. This is general information. Talk with your tax professional about your own situation.
Plant a blessing
Aspergillium proudly helps families and donors get started with Multiply Good. Visit Multiply Good to give, or to learn how to take part as a family, school, parish, or organization.
Links open Multiply Good's website in a new tab.
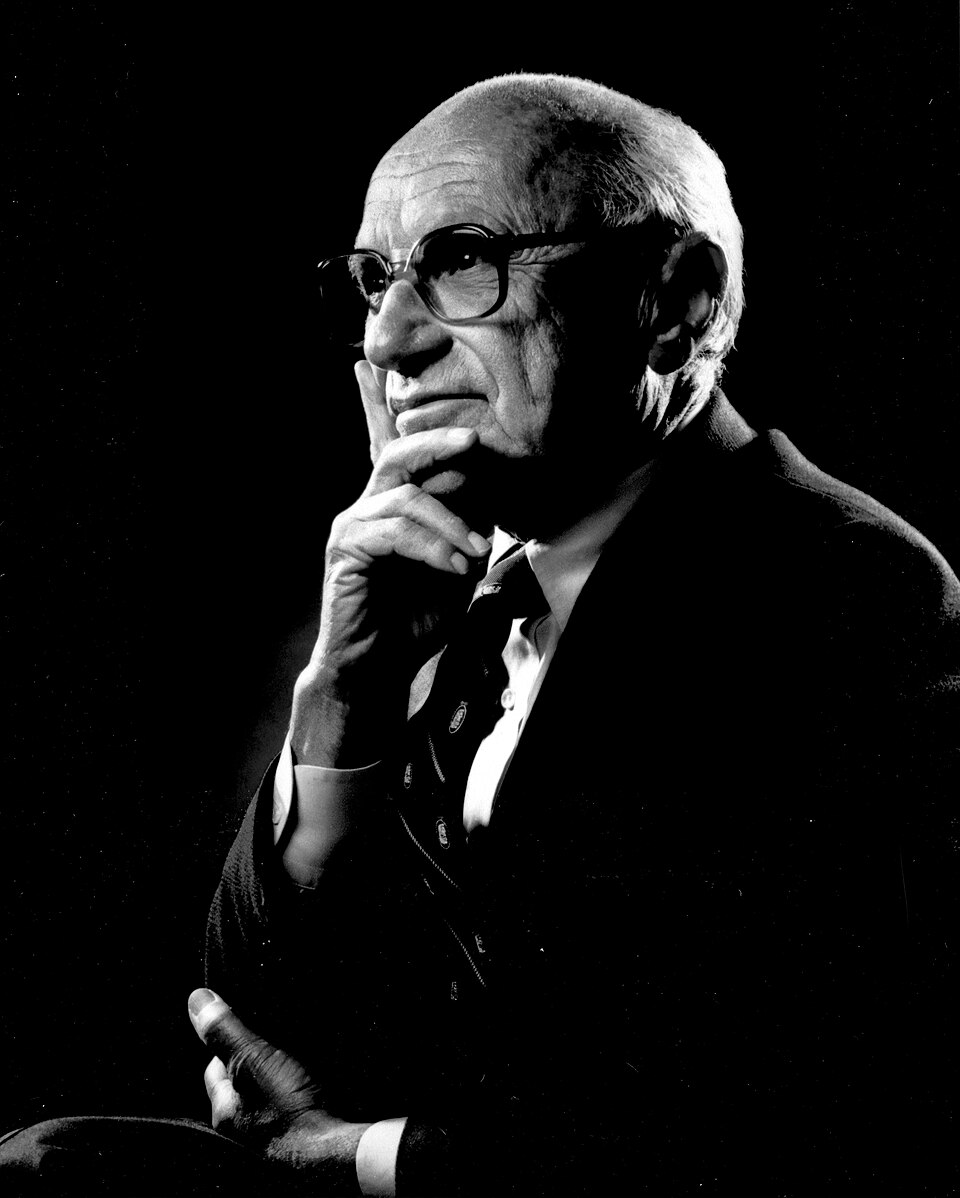
1955
Governments could require a minimum level of education which they could finance by giving parents vouchers redeemable for a specified maximum sum per child per year if spent on “approved” educational services. Parents would then be free to spend this sum and any additional sum on purchasing educational services from an “approved” institution of their own choice.
Milton Friedman, “The Role of Government in Education,” 1955.
In that essay he separated two jobs: paying for a minimum education, and running the schools. Government, he wrote, could do the first by giving parents a voucher for an approved school they choose, including a private or nonprofit school, and limit itself to checking minimum standards. He pointed to the GI Bill after World War II as the working model: a set sum a student could spend at a school they chose.
He and Rose Friedman kept making that case for decades. In 1996 they founded the Friedman Foundation for Educational Choice.
The federal scholarship tax credit that begins in 2027 is a later statute, not this 1955 proposal. Aspergillium is not a scholarship organization.
About us
Aspergillium is a national sales, marketing, and distribution company. We help families, donors, schools, and parishes across the country understand the new federal scholarship tax credit, and we proudly help them get started with Multiply Good.
Our name comes from the aspergillum, the vessel used to sprinkle holy water in blessing. We see this new law the same way: a chance to scatter small gifts widely so that they take root and grow into something lasting in the lives of children and families.
We're rooted in faith and committed to doing this work with honesty, clarity, and care, for every family, whatever school they choose.
Clear, honest information. No hype.
Guided by service to families and the common good.
Helping communities in every participating state.
Donors, families, schools, parishes, and organizations can get answers and get started through Multiply Good.